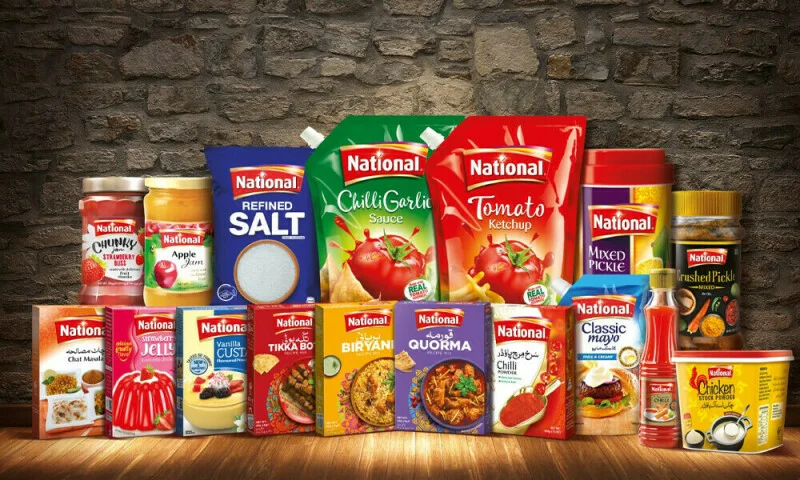
National Foods Limited has witnessed a ~17% decline in its share price calendar year to date, against a meager ~1% decline in the KSE-100 Index, according to a research note by Insight Securities.
The brokerage attributes the underperformance primarily to lower-than-expected earnings driven by margin compression in 4QFY26, alongside the loss of the company’s Shariah-compliant status after proceeds from the A1 Cash & Carry divestment were placed in conventional treasury instruments.
Gross margins fell to around 34% in 4QFY26 from about 39% in the first nine months of the year, as geopolitical tensions raised raw material, packaging and freight costs while also disrupting export sales. The company initially absorbed these pressures.
Margins have begun to recover, rising 106 basis points quarter-on-quarter to roughly 35% in 1QFY27. Management has secured raw and packaging material prices, renegotiated freight-sharing arrangements with distributors and continued efficiency improvements at the Faisalabad facility. A planned capital expenditure of about Rs4 billion is expected to further support operational gains.
China blocks SoftBank’s $5.4bn deal for ABB robotics business
Insight Securities expects average gross margins of 39% in FY27, with management targeting around 40%. On this basis, the brokerage forecasts earnings per share of Rs28.6 in FY27, up from Rs24.3 in FY26. It reiterated a BUY rating with a December 2026 sum-of-the-parts target price of Rs479 per share, implying 49% upside from the last close of Rs321.9.
On Shariah compliance, the company is working with its advisers to shift the divestment proceeds into compliant instruments that are expected to deliver similar returns (currently a minimum of 8%). Management anticipates regaining Shariah-compliant status in the coming months. The funds remain earmarked for acquisitions and strategic expansion.
Growth initiatives include roughly 25 new product launches in FY26 and a similar or higher number planned for FY27, focused on higher-contribution items. Internationally, the company aims to raise exports to about $30 million by 2030. It already operates a logistics hub in Canada and plans additional hubs in the US and UK to improve distribution.
While near-term geopolitical risks remain, Insight Securities sees product innovation, better cost pass-through and broader distribution supporting an earnings recovery.
You may also like
-
SECP Seeks Export Records from Seven Banks in SE Fruits IPO Probe
-
GTR Tyres participating in Automechanika Dubai 2026
-
Lithium Levels Discoverd at Khairpur, Sindh, are Above Global Benchmarks, OGDC
-
PSX gains 7,478 points in week falling oil prices amid US election
-
CCP Approves Nestlé–Platinum Equity Joint Venture for Waters and Beverages Business
1 thought on “National Foods stock falls 17% this year as margins compress, Shariah status lost”
Comments are closed.