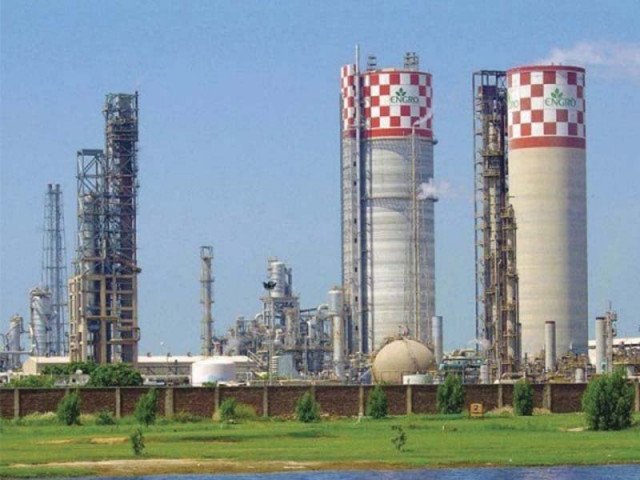
Engro Holdings’ LNG terminal profitability declined in the third quarter of 2026. Fewer vessel arrivals amid geopolitical tensions and a higher effective tax burden affected earnings. However, the company reported continued progress in its other businesses, including telecommunications infrastructure, power, mining and polymer.
Management said the minimum tax rate had fallen from 15% to 12%. However, changes introduced in the June 2025 budget kept the effective tax burden elevated.
The terminal continues to operate under a take-or-pay arrangement. A temporary relief on capacity payments had previously been granted in consultation with the government and other terminals. That relief has now ended, and the original contractual terms have resumed.
Engro Holdings Reports Higher Earnings Per Share
Engro Holdings posted consolidated profit after tax of Rs17.98 billion for the third quarter. Of this amount, Rs10.47 billion was attributable to the company’s owners.
Earnings per share increased to Rs8.86, compared with Rs6.08 in the corresponding period last year. The company did not announce a dividend for the quarter.
Towers Business Eyes Growth From 5G Expansion
Management expressed confidence in the connectivity business. The ongoing 5G rollout is creating new opportunities for tower sharing and additional colocation services.
The tenancy ratio stood at 1.36 times. Management aims to increase it to between 1.37 and 1.38 times by December 2026.
Following the 5G rollout, the company received more than 2,000 requests for power upgrades. It has completed over 1,200 upgrades and expects to upgrade another 3,000–4,000 sites over the next year. This would take total 5G-enabled upgrades to approximately 4,000–5,000 sites.
The proposed Ufone-Telenor merger could result in the loss of 500–600 tower sites. However, management expects gross additions of 1,200–1,500 sites to offset the potential impact.
Engro Holdings is also assessing participation in the proposed carve-out of Orion Towers. It is considering either an acquisition or a partnership. The company currently holds around 33% of Pakistan’s tower market.
Meanwhile, two remaining instalments payable to Jazz under the Deodar transaction total approximately Rs11–12 billion. These payments fall due in December 2026 and January 2027.
Fauji Foundation Acquires 19.70% Stake in Pearl-Continental Hotels Owner PSEL
Power and Mining Businesses Maintain Strong Performance
Engro Holdings’ power and mining operations delivered strong results during the first nine months. Healthy operations, improved collections and dividend inflows supported performance.
Government payment collections remained strong at approximately 98–99%. Load factors also maintained healthy levels during the period.
In another development, Sindh Engro Coal Mining Company (SECMC) successfully completed its Phase III expansion. This marks further progress in the company’s mining operations.
Polymer Business Reaches Cash Breakeven
The polymer business achieved cash breakeven during the nine-month period. This compares with a cash outflow of approximately Rs2 billion in the same period last year.
Sales volumes and margins remained broadly stable. Domestic sales also performed relatively well. However, international margins continued to stay below historical averages despite some improvement.
Management aims to maintain breakeven and prevent further cash outflows until global market conditions improve.
Separately, the proposed divestment of Engro Polymer and Chemicals Limited (EPCL) is progressing. The company expects the process to conclude within three to four months, potentially by the end of the first quarter of 2027.
Vopak Secures 30-Year Agreement With Port Qasim Authority
Engro Holdings’ Vopak business has secured a 30-year renewal of its Implementation Agreement with the Port Qasim Authority. The agreement provides long-term operational visibility.
However, profitability is expected to decline under the renewed arrangement. Upfront payments, royalties and revenue-sharing obligations will increase the cost burden.
Management expects the business to remain profitable, although earnings will face pressure in the initial years. The upfront payment was entirely debt-funded, resulting in higher finance costs.
The company is also exploring new growth opportunities. These include LPG and refrigerated LPG storage, additional tank capacity and expansion of existing operations.
Fauji Foundation Acquires 19.70% Stake in Pearl-Continental Hotels Owner PSEL
Diversified Businesses Face Different Earnings Trends
Engro Holdings’ latest performance reflects contrasting conditions across its business segments. Lower LNG vessel arrivals and higher taxes have pressured terminal profitability. Meanwhile, the towers business is positioning itself to benefit from 5G expansion.
Power and mining operations have maintained strong performance, while the polymer business has reached cash breakeven. Vopak’s long-term agreement offers greater visibility, although higher financing and contractual costs may weigh on near-term earnings.
You may also like
-
Mustafa Ramday appointed Chairman of the Board of Management of PSO
-
Pakistan Trade Deficit Jumps to $14.6 Billion
-
Pakistan and Türkiye Set to Revive Landmark Offshore Exploration as Seismic Vessel Arrives in Karachi between November 17-20, 2026
-
Profit taking push PSX down nearly 1,500 points
-
Chairman Punjab Revenue Authority (PRA) directs hotel owners to ensure 100% installation of E-IMS by the end of this month*
1 thought on “Engro Holdings LNG Terminal Profitability Falls on Lower Vessel Arrivals and Higher Taxes”
Comments are closed.