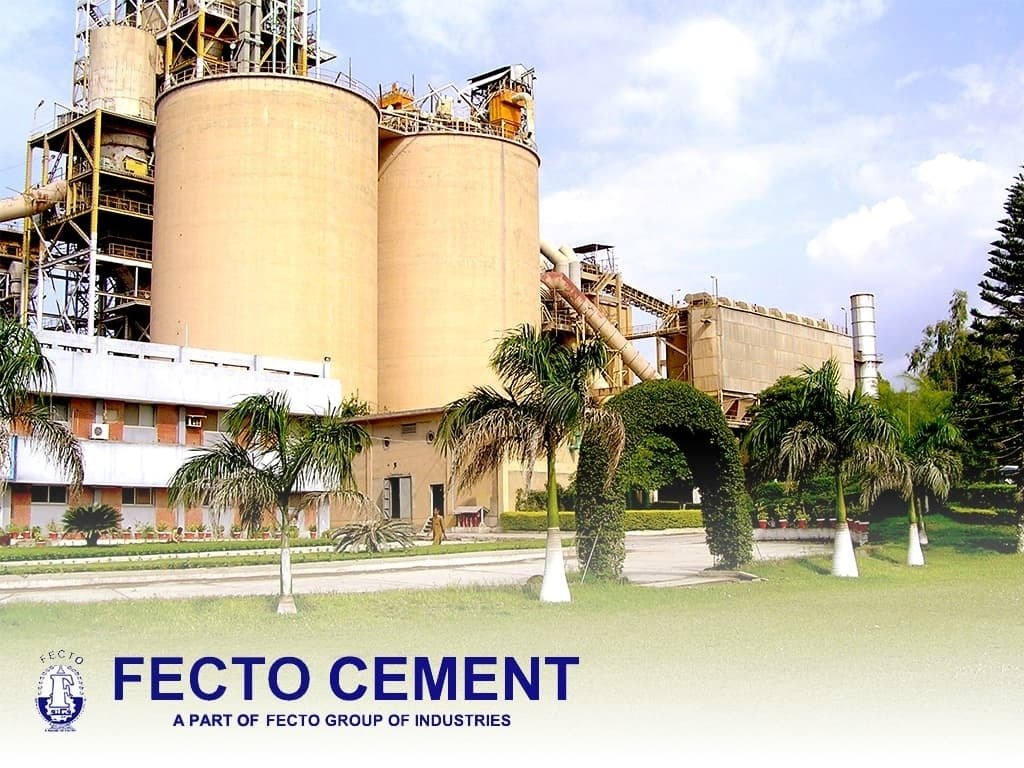
Fecto Cement Limited (FECTC) reported a sharp drop in profitability in the first quarter of FY27, with profit after tax falling to roughly PKR 111 million from PKR 208 million in the same period last year.
The decline came as total dispatches decreased about 2.2 percent year-on-year, pulling the company’s market share down to 1.81 percent from 1.92 percent a year earlier, as per Taurus Securities.
Higher input costs weighed heavily on margins. Gross margin compressed to around 10.1 percent in 1QFY27 from 18.6 percent in the corresponding quarter of FY26, even though retention prices rose about 8.3 percent year-on-year to roughly PKR 793 per bag.
Coal and fuel costs climbed 27 percent year-on-year. Average coal cost stood at about PKR 55,900 per ton in the quarter, up 26.7 percent from a year earlier, and has since moved above PKR 60,000 per ton. The company used a 60 percent local and 40 percent imported coal mix, with local coal averaging around PKR 57,000 per ton and imported coal near PKR 63,000 per ton. Limestone purchased from the market cost between PKR 1,000 and PKR 1,100 per ton.
Power costs also rose. Average power cost per ton of clinker increased about 21 percent year-on-year to roughly PKR 10,700. Renewable energy’s contribution to the power mix fell to 40.4 percent in 1QFY27 from 45.5 percent a year earlier, after having improved to 44.5 percent in FY26. The current mix comprises 33.5 percent from waste-heat recovery, 6.9 percent from solar and 59.6 percent from WAPDA.
On the efficiency side, the company reduced coal consumption per ton of clinker by about 3 percent year-on-year to roughly 143.7 kg. Management expects to add 5 MW of solar capacity by June 2027, taking total solar capacity to 10 MW, and plans to further lower coal use while raising the share of renewables to control energy costs.
Regionally, Khyber Pakhtunkhwa and the Federal Capital accounted for most of the company’s sales. Three major customers each contributed more than 10 percent of FY26 sales. The company’s current major projects include construction of dams, hydropower schemes and other large infrastructure works.
The results underscore the pressure higher coal, transport and power costs continue to place on cement producers, even as retention prices move higher. Management’s stated focus remains on reducing coal consumption per ton of clinker and increasing reliance on renewables.
You may also like
-
SBP Liquidity Injection: Central Bank Injects Rs1.021 Trillion Into Banking System
-
Gold Prices: Gold Falls Rs700 Per Tola in Pakistan
-
PTA SIM Limit: Regulator Considers Reducing Voice SIMs to Three per CNIC
-
Zardari-Shehbaz Meeting: Leaders Discuss Political, Economic and Security Situation
-
Fiscal Surplus: Pakistan Records 40% Decline in First Quarter FY27