Breaking News

Borrowing Strategy Shift: Pakistan Targets Dollar-Settled Rupee Bonds
Breaking News

Borrowing Strategy Shift: Pakistan Targets Dollar-Settled Rupee Bonds

Pakistan plans rupee-denominated, dollar-settled bond, says Aurangzeb Pakistan Plans New Rupee-Linked Dollar-Settled Bond Pakistan is preparing to introduce a new rupee-denominated bond that would be settled in US dollars, as the government looks to diversify its borrowing sources and reduce its dependence on the domestic banking system. Finance Minister Muhammad Aurangzeb disclosed the plan while addressing the Asian Development Bank’s “Mobilising Private Capital: National Strategic Dialogue on PPPs and Privatisation” in Islamabad. According to the minister, institutions have already been mandated to work on the proposed instrument. However, the government has not yet disclosed its expected size, maturity or issuance timeline. Government Seeks to Reduce Reliance on Banks Aurangzeb stressed that relying heavily on banks to meet the government’s borrowing requirements is not sustainable over the long term. The government is therefore looking to deepen Pakistan’s debt capital market and attract a wider range of institutional investors, including insurance companies and non-bank financial institutions. A broader investor base could give the government more options for raising funds while reducing pressure on commercial banks to absorb a large share of public-sector borrowing. New Bond Comes After $3 Billion Eurobond The announcement follows Pakistan’s successful return to international debt markets with a $3 billion Eurobond issuance. The government raised $1.75 billion through a 5.5-year bond carrying a 7.5 per cent coupon and another $1.25 billion through a 10-year bond with a 7.9 per cent coupon. The transaction attracted nearly $6 billion in orders from institutional investors across global markets, highlighting strong demand for Pakistan’s latest international debt offering. The strong order book has provided the government with an opportunity to explore additional financing structures beyond conventional Eurobonds. Pakistan Looks to Broaden Its Investor Base The proposed rupee-linked, dollar-settled instrument is part of a wider effort to diversify Pakistan’s capital-market investor base. Aurangzeb said the government needs to develop debt capital markets that can attract investors beyond traditional banking institutions. The Ministry of Finance has also been working to broaden retail access to government securities. The minister said the ministry had collaborated with JazzCash, while the State Bank of Pakistan had launched an application allowing individuals to invest directly in government securities. These measures could gradually expand participation in government debt and create additional channels for mobilising domestic savings. Government Explores Tokenisation of Eurobonds Pakistan is also examining newer financing mechanisms, including the potential tokenisation of some existing Eurobond debt. Aurangzeb referred to Hong Kong’s experience with tokenised financial instruments and said Pakistan had attempted to explore a similar approach for part of its existing Eurobond debt. If developed successfully, tokenisation could offer another route for improving access to government securities and modernising the country’s debt-market infrastructure. Foreign Exchange Reserves Target Set at $21 Billion The finance minister also provided an update on Pakistan’s foreign exchange position. According to Aurangzeb, foreign exchange reserves stood at $18.4 billion as of June 30, with the government targeting $21 billion by the end of the current fiscal year. He said reaching that level would provide a little more than three months of import cover, which he described as a good international benchmark. The reserve target is particularly important as Pakistan continues to manage external financing requirements and maintain stability in its balance of payments. US-Iran Conflict Remains an Economic Risk Aurangzeb also said the government was closely monitoring the ongoing US-Iran conflict because of its potential impact on Pakistan’s growth and inflation projections. Geopolitical tensions can affect Pakistan through higher energy prices, supply-chain disruptions and increased pressure on external financing requirements. For policymakers, maintaining adequate foreign exchange buffers and diversifying financing sources therefore remains important as global risks remain elevated. A Shift Toward More Diversified Financing Pakistan’s latest borrowing strategy suggests a broader effort to move beyond dependence on a single source of financing. The successful $3 billion Eurobond has reopened international market access, while the planned rupee-denominated, dollar-settled bond could offer a different structure for attracting investors. At the same time, efforts to bring insurance companies, non-bank financial institutions and retail investors into government securities could help build a deeper domestic capital market. The success of these initiatives will ultimately depend on investor confidence, pricing, currency risk management and the government’s ability to maintain fiscal and external stability.
Karachi Markets Shut Down as Traders Back JI Nationwide Strike Call
Breaking News

Karachi Markets Shut Down as Traders Back JI Nationwide Strike Call

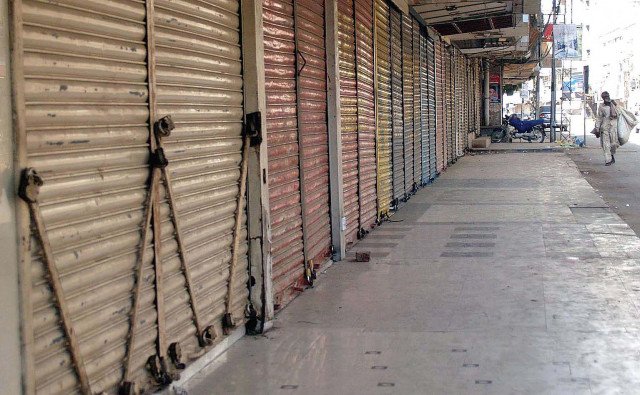
Major Markets Back September 3 Strike Karachi’s business community is gearing up for a major shutter-down strike on September 3, with several prominent trader organisations announcing support for Jamaat-e-Islami’s nationwide protest against inflation, taxes and rising fuel-related costs. The All City Traders Alliance and All Iron and Steel Merchants Association have announced that markets affiliated with them will remain closed. Their support adds to the growing number of commercial areas preparing to shut their businesses for the day. Dozens of Markets Expected to Close The strike has gained support from traders across several parts of Karachi. Earlier, representatives of 43 markets, along with electronics dealers and traders from Clifton and DHA, had agreed to participate. Markets and shopping centres expected to remain closed include Panorama Centre, Atrium Mall, Madina City Mall, Victoria Market, Zainab Market, International Market, Clifton Market, Gulf and Cliff the Plaza. Electronics and mobile markets are also expected to participate. Traders Raise Concerns Over Taxes and Inflation Trader bodies supporting the strike are demanding government action to ease the economic pressure on businesses and consumers. Their concerns include additional taxes, inflation and higher petroleum-related charges. The Karachi Electronics Dealers Association has also backed the protest, citing the petroleum levy, inflation and concerns surrounding independent power producers. The growing participation reflects increasing frustration among sections of the business community over the rising cost of doing business. Wholesale Food and Medicine Markets to Stay Open The shutdown, however, will not cover every part of Karachi’s commercial network. The Wholesale Grocers Association has announced that wholesale commodity markets, including Jodia Bazaar, will remain open and continue normal trading operations. Similarly, the Wholesale Karachi Pharma Organisation has decided to keep medicine markets operational on September 3. This means Karachi’s strike will result in a mixed picture, with many retail and commercial markets closing while key wholesale food and pharmaceutical markets continue operating. JI Warns of Wider Protest Campaign Jamaat-e-Islami chief Hafiz Naeemur Rehman has warned that the protest campaign could expand if the government does not address the party’s demands. The party has called for changes to petroleum-related charges, a review of agreements with independent power producers and measures to control inflation. It has also indicated that options including a long march and sit-ins in Islamabad and Rawalpindi could remain on the table. Karachi’s Business Community Under Pressure The planned shutdown highlights the wider economic pressures facing Karachi’s traders. While some associations have chosen to protest through closure, others have opted to maintain operations, particularly in sectors supplying essential goods. The September 3 strike will therefore serve as an important indicator of the level of support among Karachi’s commercial community for demands related to taxation, fuel costs and inflation. For businesses already dealing with higher operating expenses and weaker purchasing power, the central concern remains whether government policy can provide meaningful relief without creating further pressure on the economy.

Maple Leaf Moves to Swallow Pioneer: 2.65 Shares for Every PIOC Stock
Breaking News

Maple Leaf Moves to Swallow Pioneer: 2.65 Shares for Every PIOC Stock

Maple Leaf Approves Pioneer Cement Merger Maple Leaf Cement has moved closer to fully absorbing Pioneer Cement after its board approved a Scheme of Arrangement on September 2, 2026. Under the proposed arrangement, Pioneer Cement’s entire business, including its plants, assets, liabilities, rights and obligations, will be transferred to Maple Leaf Cement. Pioneer will subsequently be dissolved without winding up. The move would effectively bring Pioneer under a single listed structure rather than continuing to operate it as a separate listed subsidiary. Shareholders to Receive 2.65 MLCF Shares Under the proposed share-swap arrangement, Pioneer Cement shareholders other than Maple Leaf Cement itself will receive 2.65 ordinary shares of Maple Leaf Cement for every one PIOC share. The transaction will result in the issuance of approximately 136.17 million new Maple Leaf shares. Pioneer’s existing shares, including those held by Maple Leaf, will be cancelled as part of the amalgamation. Maple Leaf Already Controls Most of Pioneer The structure of the transaction is important because Maple Leaf Cement and its group already control approximately 88.28% of Pioneer Cement following the takeover completed in February. The new Maple Leaf shares will therefore primarily go to Pioneer’s remaining minority shareholders and relevant group entities rather than representing a fresh acquisition of control. Based on Maple Leaf Cement’s share price of around Rs97.4, the swap ratio implies a value of approximately Rs258 per Pioneer share. That is broadly in line with Pioneer’s prevailing market price and does not represent a major premium for shareholders. The Rs478 Cash Offer Puts the Swap in Context The proposed merger also needs to be viewed against Maple Leaf’s earlier cash offer. Maple Leaf acquired control of Pioneer Cement at approximately Rs478.43 per share only months ago. For investors who did not participate in that offer and continued holding PIOC shares, the proposed arrangement now means exchanging their Pioneer shares for Maple Leaf stock at a substantially lower implied value. As a result, the 2.65-share ratio may be favourable relative to Pioneer’s current market price, but it is considerably below the earlier cash acquisition price. A Merger of Control Rather Than Equals This is effectively a parent company consolidating its subsidiary rather than a merger between two independent businesses. Maple Leaf already consolidates Pioneer Cement’s financial results, while management had previously indicated that a legal merger could take place by late 2026 or early 2027. The proposed arrangement now provides a formal structure for completing that process. The combined production capacity is significant. Maple Leaf’s Mianwali complex has capacity of around 7.8 million tonnes, while Pioneer’s Jauharabad facilities add approximately 5 million tonnes. Together, the two businesses would approach 13 million tonnes of annual capacity, strengthening Maple Leaf’s position in Pakistan’s northern cement market. Operational Synergies Could Be the Bigger Prize The two cement operations are located relatively close to each other, with the plants separated by roughly 80 kilometres. This proximity could create opportunities to improve logistics, coordinate coal procurement and optimise kiln utilisation. For Maple Leaf, eliminating a separate listed structure could also reduce administrative complexity and allow the combined business to operate under a more streamlined balance sheet. The share-swap ratio is also slightly above the 2.1-to-2.6 range that had been considered reasonable by Topline Securities, placing the proposed exchange at the upper end of that range. Merger Still Needs Regulatory Approval The board approval does not complete the transaction. Shareholders of both companies will need to approve the arrangement, while the relevant regulatory approvals will also be required. The Lahore High Court must sanction the scheme under Sections 279 to 283 of the Companies Act. A joint petition is expected to be filed with the court in due course. The proposed effective date is July 1, 2026, which would allow the companies to combine their financial reporting from the beginning of the fiscal year if the arrangement receives the necessary approvals. Until then, Pioneer Cement remains a separately listed company on the Pakistan Stock Exchange. Maple Leaf Shareholders Face Around 13% Dilution The issuance of approximately 136.17 million new Maple Leaf shares will dilute existing shareholders. Against Maple Leaf’s current share count of roughly 1.05 billion, the new shares represent dilution of around 13%. However, Maple Leaf already owns the overwhelming majority of Pioneer, meaning much of the economic benefit of the subsidiary is already reflected in the parent’s financial position. The consolidation would also eliminate related-party transactions between the two companies. For example, Pioneer had recently approved a financing facility of up to Rs4 billion for its parent. Following amalgamation, such transactions would effectively become internal to the combined business. North Pakistan’s Cement Market Continues to Consolidate The proposed merger comes as Pakistan’s cement industry continues to move toward greater consolidation. With Lucky Cement and Bestway maintaining strong positions, the combined Maple Leaf-Pioneer operation would become another major player in the northern cement market. The disappearance of Pioneer’s independent listing will also change how investors gain exposure to the business. Investors currently holding PIOC shares would receive Maple Leaf shares under the proposed arrangement, effectively replacing their direct exposure to Pioneer with ownership in the larger combined company. What the Merger Means for Investors For Maple Leaf shareholders, the merger could simplify the group structure while creating opportunities for operational efficiencies across two sizeable cement operations. For Pioneer’s remaining minority shareholders, the key issue is whether the 2.65-share exchange ratio fairly reflects the value of their investment. The proposed arrangement still has several steps to clear before it becomes effective, particularly shareholder and court approval. If completed, Pioneer Cement’s separate identity on the stock exchange would disappear, leaving Maple Leaf Cement with a larger and more integrated cement business. The plants may remain in the same locations, but the corporate structure behind them would be significantly different.

Gold Prices Slip to Three-Week Low as Middle East Tensions Raise Rate-Hike Concerns
Breaking News

Gold Prices Slip to Three-Week Low as Middle East Tensions Raise Rate-Hike Concerns

Gold prices fell to their lowest level in more than three weeks on Wednesday as renewed US-Iran tensions pushed oil prices higher and increased concerns about inflation and interest rates. Gold Faces Fresh Pressure Spot gold declined 0.6% to around $4,304 per ounce, its lowest level since August 7. US gold futures for December also dropped about 1% to $4,350.80. The decline marks gold’s fourth consecutive session of losses, with prices remaining below the closely watched 200-day moving average. Oil Prices Change the Market Outlook Renewed US-Iran hostilities have pushed oil prices higher, raising concerns that more expensive energy could reignite inflation. That matters for gold because higher inflation can strengthen expectations for tighter monetary policy. Markets are currently pricing in a significantly higher possibility of a US Federal Reserve rate hike this month. Gold does not generate interest income, so higher interest rates can make the precious metal less attractive compared with yield-generating assets. US Jobs Data in Focus Investors are also waiting for fresh US employment figures. Upcoming labour-market data could influence expectations for the Federal Reserve’s next policy decision. A weaker jobs report could reduce pressure on gold, while stronger employment data or more hawkish signals from the Fed could keep prices under pressure. What It Means for Gold Investors The latest decline shows how quickly geopolitical developments can change the direction of global markets. Although gold is traditionally viewed as a safe-haven asset, rising oil prices, higher yields and stronger rate expectations are currently outweighing that support. For now, investors are likely to remain focused on the Middle East conflict, oil prices, US inflation signals and upcoming employment data as they assess gold’s next move.

FBR Meets Rs1.71 Trillion Tax Target, But Revenue Growth Remains a Concern
Breaking News

FBR Meets Rs1.71 Trillion Tax Target, But Revenue Growth Remains a Concern

Pakistan’s Federal Board of Revenue (FBR) has met its combined tax collection target for the first two months of the current fiscal year, collecting around Rs1.722 trillion during July and August. The collection was about Rs12 billion above the Rs1.71 trillion target. However, the headline achievement masks a concern: revenue grew by only 3.3% compared with the same period last year, significantly below the 17.4% growth needed to meet the annual target. August Collection Falls Short While strong collection in July helped the FBR meet its two-month target, August performance was weaker. The FBR collected around Rs900 billion in August, against a monthly target of Rs930 billion, leaving a shortfall of approximately Rs29 billion. Income tax remained a major weakness. Collections stood at more than Rs685 billion, falling Rs74 billion below the two-month target and declining around 4% from the previous year. Sales Tax Provides Support Sales tax collections provided much of the support for the overall performance. The FBR collected around Rs719 billion in sales tax, exceeding the two-month target by Rs85 billion and registering 14% growth compared with last year. A significant portion of this revenue came from imports. Federal excise duty generated around Rs118 billion, while customs duty collection reached approximately Rs198 billion. Annual Target Remains a Challenge For FY2026–27, Pakistan has agreed with the IMF on an ambitious FBR tax collection target of Rs15.263 trillion. Reaching this figure requires tax revenues to grow by around 17.4% compared with the previous year. The current 3.3% growth rate therefore leaves a considerable gap to close in the remaining months. The IMF has also linked progress on tax collection to the country’s programme commitments, increasing the pressure on the FBR to improve revenue performance. Enforcement And Tax Base Expansion The government has introduced several measures to improve tax compliance and broaden the tax base. However, implementation remains a challenge. The FBR has made progress in integrating large retailers into its digital Point-of-Sale system, with more than 17,300 businesses integrated during FY2025–26. At the same time, some planned digital tax measures and enforcement mechanisms have faced delays. For the FBR, the challenge now is to turn early-year target achievement into sustained revenue growth. What Comes Next Meeting the first two months’ target provides some breathing space, but it does not remove the pressure on Pakistan’s tax authorities. The coming months will be critical. Stronger income-tax collection, wider documentation of the economy and more effective enforcement will be necessary if the FBR is to maintain the pace required for its annual target. For Pakistan’s fiscal position and IMF programme, the quality and sustainability of revenue growth will matter more than simply meeting individual monthly targets.

Guddu Power Plant Rehabilitation Could Cut Electricity Cost by Rs4.19 Per Unit
Breaking News, Editor pick

Guddu Power Plant Rehabilitation Could Cut Electricity Cost by Rs4.19 Per Unit

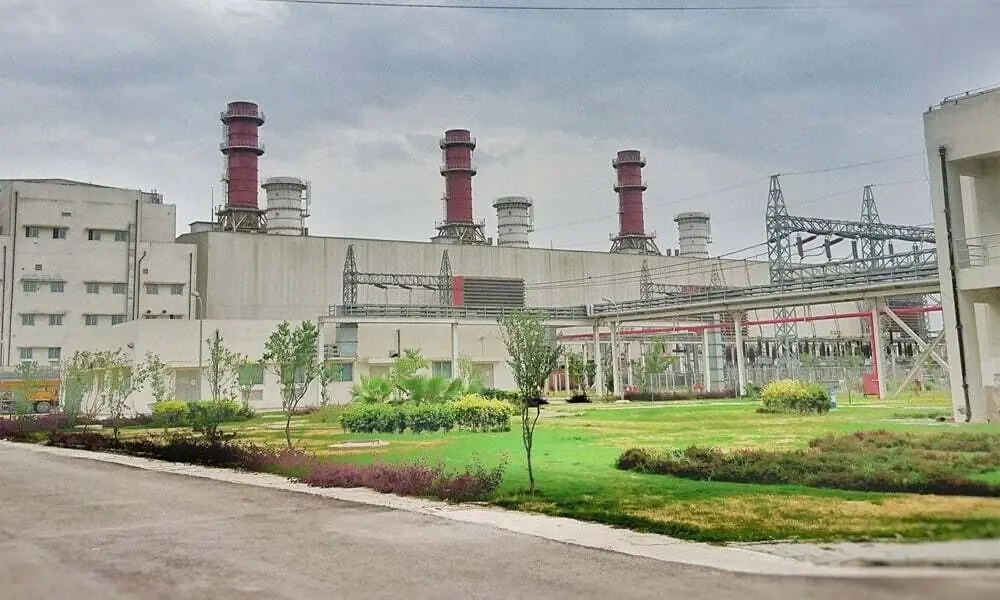
Pakistan is moving to revive one of its underutilized power assets as the Guddu Power Plant rehabilitation project enters a critical procurement phase. The rehabilitation of the fire-damaged Steam Turbine-16 could reduce the plant’s generation cost from Rs13.87 to Rs9.68 per unit, translating into savings of Rs4.19 per unit. The project could also restore an additional 297 MW of generation capacity, taking the plant from its current output of around 450 MW to its original designed capacity of 747 MW. At a time when Pakistan continues to face high electricity costs, circular debt pressures and concerns over expensive generation, the rehabilitation could provide a relatively faster route to improving the economics of existing power infrastructure. Fire-Damaged Steam Turbine Has Kept Guddu Below Its Potential The Guddu plant has been operating in open-cycle mode since July 2022, when Steam Turbine-16 and its associated generator were forced out of service following a fire. The outage has had a significant impact on the plant’s economics. Operating at approximately 450 MW has restricted the facility’s ability to benefit from combined-cycle generation, while its relatively high generation cost has placed it around 11th in the dispatch queue. This raises an important question for policymakers. Why has a major generation asset remained below its designed capacity for more than four years? The answer now appears to be a long-awaited rehabilitation process. Guddu Power Plant Rehabilitation Could Restore 747 MW Capacity Once Steam Turbine-16 is restored, the plant is expected to return to full combined-cycle operation and achieve its designed 747 MW capacity. That would mean an additional 297 MW becoming available without constructing an entirely new power plant. More importantly, the plant’s expected merit-order position could improve from approximately 11th to around 7th. A better position in the dispatch order could allow Guddu to displace more expensive electricity from the national grid. For consumers, this distinction matters. Adding generation capacity alone does not guarantee cheaper electricity. The real benefit comes when additional capacity is available at a competitive generation cost. Procurement Begins as Commissioning Is Targeted for 2028 Following technical studies, engineering reviews and comprehensive integrity assessments, authorities have prepared an EPC turnkey procurement package for the rehabilitation. International competitive bids have now been invited for the restoration of Steam Turbine-16 and associated equipment. Bidders are required to submit their proposals by October 7, 2026. The targeted commissioning date is December 2028. However, the timeline deserves scrutiny. Pakistan’s electricity sector has repeatedly suffered from delays in maintenance, rehabilitation and infrastructure projects. A commissioning target more than two years away means the country could continue carrying the economic cost of underutilized capacity for a considerable period. The government will therefore need to ensure that procurement, contract execution and project supervision remain transparent and strictly time-bound. Guddu Power Plant Rehabilitation Has Strategic Grid Importance The project’s importance extends beyond generation costs. Guddu is positioned at a critical point in Pakistan’s transmission network and the north-south power flow corridor. Restoring its full generation capability could provide the national grid with greater operational flexibility and resilience. The additional 297 MW could also become particularly valuable during periods of high demand, provided the transmission system can efficiently absorb and distribute the additional electricity. Existing Assets May Offer Pakistan a Cheaper Power Solution The Guddu Power Plant rehabilitation highlights a broader issue facing Pakistan’s energy sector. The country does not necessarily need to rely only on new generation projects to address electricity shortages and high costs. There may be significant value locked inside existing plants that are operating below capacity because of technical failures, outdated equipment or delayed maintenance. Rehabilitating such assets can potentially be faster and less capital-intensive than building new generation facilities from scratch. But the government must avoid treating rehabilitation as an end in itself. The real test will be whether Guddu actually delivers the projected Rs4.19 per unit reduction, restores 297 MW of capacity and maintains reliable operations after commissioning. If those targets are achieved, the project could become a strong example of how Pakistan can extract greater value from its existing power infrastructure while putting downward pressure on the cost of electricity.

Auto Policy 2026-31: PAAPAM Demands Higher CBU Duties
Breaking News

Auto Policy 2026-31: PAAPAM Demands Higher CBU Duties

Pakistan’s automotive parts industry has called for a major rethink of import tariffs as the government prepares the Auto Policy 2026-31, warning that unrestricted imports could weaken local manufacturing, investment and employment. The Pakistan Association of Automotive Parts and Accessories Manufacturers, known as PAAPAM, has submitted a position paper for consideration in the formulation of the new policy. The association wants higher duties on completely built units, or CBUs, and selected localised automotive parts, while demanding minimal or zero duties on raw materials. The proposal could become one of the most important tariff debates under the Auto Policy 2026-31, as Pakistan attempts to balance cheaper vehicles for consumers with the need to build a stronger domestic manufacturing base. Auto Policy 2026-31 Faces a Protection Versus Competition Test PAAPAM argues that the tariff structure should encourage manufacturers to produce more components locally rather than depend heavily on imported vehicles and parts. Its proposed approach is straightforward. Raw materials needed for domestic production should face minimal or zero customs duties, while fully built imported vehicles should carry higher duties. Localised parts should also receive tariff protection against competing imports. From an industrial policy perspective, the argument has merit. A country that wants to expand manufacturing cannot expect local suppliers to compete indefinitely against imported finished products while simultaneously facing high costs for production inputs. However, the government must be careful not to turn the Auto Policy 2026-31 into another protectionist framework that shields inefficient manufacturers indefinitely. Tariff protection can help an emerging industry develop, but excessive protection can also reduce competition, keep prices high and give manufacturers little incentive to improve quality or productivity. PAAPAM Highlights 300,000 Direct Automotive Jobs PAAPAM says the automotive parts industry and wider ecosystem represent a significant source of employment in Pakistan. According to the association, the sector generates around 300,000 direct jobs and supports another 1.5 million indirect livelihoods. Its members include more than 300 companies, while around 1,200 firms operate across the broader automotive ecosystem. Pakistan currently has 13 local car assemblers, more than 50 motorcycle and electric bike assemblers, 10 truck and bus assemblers and three tractor assemblers. These figures underline why the tariff decisions under the Auto Policy 2026-31 matter beyond vehicle prices. Changes in import duties could affect factories, vendors, logistics companies, dealerships and thousands of workers connected to the automotive supply chain. Auto Policy 2026-31 Must Avoid Another Localisation Trap The biggest question for policymakers is whether higher import duties will actually produce globally competitive Pakistani manufacturers. Pakistan has used localisation policies for decades, yet the automotive industry continues to face concerns over limited competition, high vehicle prices, supply constraints and dependence on imported components. That makes PAAPAM’s demand worthy of scrutiny. Protecting local parts manufacturers without demanding measurable improvements in productivity, quality, exports and technology transfer could simply shift the cost onto consumers. The new policy should therefore link tariff protection with clear performance requirements. Manufacturers receiving protection should have incentives to increase local value addition, develop export markets, improve quality standards and reduce production costs. Auto Policy 2026-31 Could Reshape Pakistan’s Automotive Industry PAAPAM wants the government to finalise automotive import tariffs in a way that supports localisation, exports, investment, employment and long-term industrial growth. The proposal places a difficult choice before policymakers. Higher CBU duties could encourage local production, but consumers could ultimately pay more if competition remains weak. The real test of the Auto Policy 2026-31 will therefore not be whether it protects the automotive industry. It will be whether that protection creates a more competitive industry. Pakistan needs an automotive policy that rewards manufacturing efficiency rather than simply insulating producers from imports. If the government gets that balance right, the new policy could strengthen the domestic auto supply chain and create a foundation for exports. If it gets it wrong, Pakistan could end up protecting an industry without making it genuinely competitive.

FBR Shortfall Remains the Weak Spot as IMF Prepares Fourth Review
Breaking News

FBR Shortfall Remains the Weak Spot as IMF Prepares Fourth Review

Pakistan is heading toward another important review of its IMF programme, with weak Federal Board of Revenue (FBR) tax collection emerging as one of the main concerns. An IMF staff mission is expected to visit Pakistan in September for the fourth review of the $7 billion Extended Fund Facility (EFF) and the third review of the $1.4 billion Resilience and Sustainability Facility (RSF). IMF Review to Test Pakistan’s Economic Performance The upcoming review will assess Pakistan’s performance against targets set for the end of March and June 2026. Finance officials have indicated that the mission could arrive during the second week of September, although the final dates have not yet been confirmed. The review follows the IMF’s May approval of the previous EFF and RSF assessments, which unlocked around $1.1 billion and $220 million respectively. Most IMF Targets Appear to Be on Track Available estimates suggest Pakistan is likely to meet most of the programme’s key quantitative targets. Net international reserves are believed to have remained above the IMF’s required floors, while the State Bank of Pakistan’s net domestic assets also appear to be within the agreed limits. Foreign-currency swap levels have similarly remained below the programme ceilings. Pakistan has also performed strongly on the primary surplus, with estimates indicating that the government exceeded the IMF’s targets for both March and June. Government guarantees and targeted spending under the Benazir Income Support Programme also appear to remain within the agreed parameters. FBR Revenue Collection Remains a Concern The biggest weakness is Pakistan’s tax collection performance. FBR collections recorded a substantial shortfall during the first half of FY26, while the full-year collection also remained below the original target. Although FBR collection is an indicative target rather than one of the key quantitative performance criteria for the review dates, continued weakness in revenue mobilisation remains important for Pakistan’s wider IMF commitments. A potential recovery through the Super Tax litigation could provide some relief, but it is unlikely to completely eliminate the revenue gap. Structural Reforms Still Matter The IMF review will not be limited to fiscal numbers. Structural reforms are also expected to remain an important part of discussions. Key areas include amendments concerning the Sovereign Wealth Fund, remaining state-owned enterprise legislation, energy-sector reforms, privatisation measures and the IMF-backed governance and anti-corruption diagnostic. If Pakistan meets its main quantitative commitments, some indicative targets and structural benchmarks could be extended or adjusted for the next phase of the programme. What the IMF Review Means for Pakistan A successful review would help keep upcoming EFF and RSF disbursements on track and could provide further support for investor confidence and Pakistan’s improving credit outlook. However, persistent weakness in tax collection could keep pressure on the government to strengthen revenue mobilisation. Any significant structural or fiscal slippage could also result in tighter conditionality during FY27. For Pakistan, the upcoming IMF review is therefore less about negotiating an entirely new programme and more about demonstrating that the country can consistently deliver on its existing commitments. The Road Ahead Pakistan appears to have performed well against several major IMF targets, particularly its primary surplus, reserves and social-protection spending. The FBR shortfall, however, remains a clear vulnerability. The September review will provide an important test of whether Pakistan can maintain fiscal discipline while making progress on deeper economic reforms. Sustained improvement in tax collection and structural implementation will be essential if the country wants to reduce its dependence on repeated stabilisation programmes over the longer term.

K-Electric Withdraws From Fesco Privatisation Bid Over Unaudited Accounts
Breaking News

K-Electric Withdraws From Fesco Privatisation Bid Over Unaudited Accounts

K-Electric has withdrawn from the privatisation process for Faisalabad Electric Supply Company (Fesco) after it was unable to provide audited financial statements for the past three years. The Privatisation Commission has prequalified 10 firms to move forward with the Fesco bidding process. K-Electric was not included after withdrawing its expression of interest. Pending NEPRA Tariff Keeps K-Electric Accounts Unaudited K-Electric said its financial statements remain unaudited because the National Electric Power Regulatory Authority (NEPRA) has yet to finalise the company’s Multi-Year Tariff. The power utility said the delay is beyond its control and confirmed that its decision to withdraw was directly linked to the unavailability of audited accounts. Despite exiting the Fesco process, K-Electric said it remains interested in opportunities that can create value for its stakeholders. 10 Firms Prequalified For Fesco Sale The Privatisation Commission received 12 expressions of interest and approved 10 bidders after reviewing their eligibility. The prequalified bidders include three Turkish companies — Aktor Elektrik Enerji Yatirimlari, Genvera Enerji and Cengiz Enerji — along with several major Pakistani business groups. Engro Energy, Sapphire Fibres, a Hub Power Holdings-led consortium, Shirazi Investments, Maple Leaf Cement, Kohinoor Textile, a Pakgen-led consortium and Artistic Milliners are among the firms moving to the next stage. A Chinese company, Jiangxi Electric Power Construction Company Limited, was declared non-compliant after failing to resubmit its documentation in the required English language. Fesco Sale Moves Into Due Diligence The government plans to sell between 51% and 100% of Fesco, along with management control. The successful bidder will gain access to the Privatisation Commission’s Virtual Data Room to conduct detailed due diligence before submitting a financial offer. Fesco has assets worth around Rs290.5 billion against liabilities of Rs226.5 billion, leaving approximately Rs64 billion in net equity. The federal government will retain land valued at around Rs73 billion. Fesco is considered one of Pakistan’s more efficient state-owned distribution companies, with distribution losses reported at around 8% during the last fiscal year. K-Electric Exit Leaves Experienced Bidder Out K-Electric’s withdrawal is significant because it is currently the only Pakistani company with direct experience of operating a privatised electricity distribution business. The government is seeking private ownership and management control of stronger Discos as part of its wider power-sector reform programme. With K-Electric out of the Fesco race, the remaining bidders will now face the challenge of completing due diligence and presenting competitive offers.

PIMS Fire: Govt Announces Rs5m Compensation For Each Affected Family
Breaking News, Uncategorized

PIMS Fire: Govt Announces Rs5m Compensation For Each Affected Family

The government has announced Rs5 million compensation for each family affected by the PIMS fire that claimed the lives of 14 infants at the Pakistan Institute of Medical Sciences (PIMS) in Islamabad. Parliamentary Affairs Minister Tariq Fazal Chaudhry said the financial assistance was approved by Prime Minister Shehbaz Sharif to provide some relief to the bereaved families. Speaking to the media during a visit to PIMS, Chaudhry expressed deep sorrow over the deaths and said the 14 infants had become victims of what he described as “criminal negligence”. The minister said the government could not undo the loss suffered by the families. He acknowledged that no financial assistance could bring the deceased children back or reduce the grief of their parents. However, he said the compensation was intended to provide some immediate financial support to the affected families during an extremely difficult period. PIMS Fire Inquiry Committee To Submit Report Chaudhry said Prime Minister Shehbaz Sharif had formed an inquiry committee to investigate the incident and determine how the fire started and whether negligence contributed to the deaths. According to the minister, the committee was expected to submit its report on Thursday. The findings are likely to establish responsibility and identify officials or other on-duty personnel whose actions or omissions may have contributed to the tragedy. Chaudhry assured the affected families that those found responsible for negligence would face strict action. “All on-duty individuals found guilty of negligence will be given exemplary punishment,” he said. The minister’s remarks came as concerns grew over safety arrangements and emergency procedures at the major public-sector hospital following the deaths of the infants. Rs5m To Be Deposited In Mothers’ Accounts The parliamentary affairs minister said he had visited PIMS on behalf of the prime minister to support the affected families and oversee the distribution of the announced compensation. He said he was at the hospital to hand over a cheque to one of the affected families. The government plans to deposit the Rs5 million compensation into the bank accounts of the mothers of the deceased children. The move is aimed at ensuring that the financial assistance reaches the families directly. Chaudhry reiterated that the government understood the enormous pain caused by the deaths and said financial assistance should not be viewed as compensation for the loss itself. Govt Promises Accountability The announcement of compensation comes alongside the government’s commitment to determine responsibility for the PIMS fire. The inquiry committee’s report will be closely watched by the families and the public, particularly regarding any safety lapses or negligence identified during the investigation. The minister stressed that those responsible would not be allowed to escape accountability if the inquiry established their negligence. The tragedy has also raised questions about hospital safety protocols, emergency response systems and the protection of vulnerable patients, particularly newborns and infants. The government is now expected to review the inquiry findings and take action based on the committee’s recommendations.

Scroll to Top