Editor pick

Guddu Power Plant Rehabilitation Could Cut Electricity Cost by Rs4.19 Per Unit
Breaking News, Editor pick

Guddu Power Plant Rehabilitation Could Cut Electricity Cost by Rs4.19 Per Unit

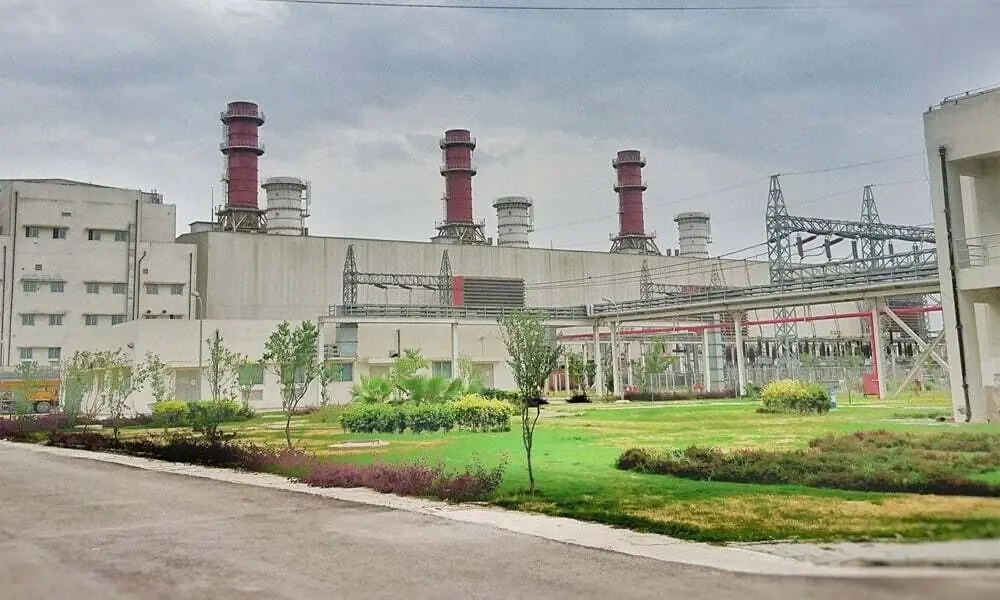
Pakistan is moving to revive one of its underutilized power assets as the Guddu Power Plant rehabilitation project enters a critical procurement phase. The rehabilitation of the fire-damaged Steam Turbine-16 could reduce the plant’s generation cost from Rs13.87 to Rs9.68 per unit, translating into savings of Rs4.19 per unit. The project could also restore an additional 297 MW of generation capacity, taking the plant from its current output of around 450 MW to its original designed capacity of 747 MW. At a time when Pakistan continues to face high electricity costs, circular debt pressures and concerns over expensive generation, the rehabilitation could provide a relatively faster route to improving the economics of existing power infrastructure. Fire-Damaged Steam Turbine Has Kept Guddu Below Its Potential The Guddu plant has been operating in open-cycle mode since July 2022, when Steam Turbine-16 and its associated generator were forced out of service following a fire. The outage has had a significant impact on the plant’s economics. Operating at approximately 450 MW has restricted the facility’s ability to benefit from combined-cycle generation, while its relatively high generation cost has placed it around 11th in the dispatch queue. This raises an important question for policymakers. Why has a major generation asset remained below its designed capacity for more than four years? The answer now appears to be a long-awaited rehabilitation process. Guddu Power Plant Rehabilitation Could Restore 747 MW Capacity Once Steam Turbine-16 is restored, the plant is expected to return to full combined-cycle operation and achieve its designed 747 MW capacity. That would mean an additional 297 MW becoming available without constructing an entirely new power plant. More importantly, the plant’s expected merit-order position could improve from approximately 11th to around 7th. A better position in the dispatch order could allow Guddu to displace more expensive electricity from the national grid. For consumers, this distinction matters. Adding generation capacity alone does not guarantee cheaper electricity. The real benefit comes when additional capacity is available at a competitive generation cost. Procurement Begins as Commissioning Is Targeted for 2028 Following technical studies, engineering reviews and comprehensive integrity assessments, authorities have prepared an EPC turnkey procurement package for the rehabilitation. International competitive bids have now been invited for the restoration of Steam Turbine-16 and associated equipment. Bidders are required to submit their proposals by October 7, 2026. The targeted commissioning date is December 2028. However, the timeline deserves scrutiny. Pakistan’s electricity sector has repeatedly suffered from delays in maintenance, rehabilitation and infrastructure projects. A commissioning target more than two years away means the country could continue carrying the economic cost of underutilized capacity for a considerable period. The government will therefore need to ensure that procurement, contract execution and project supervision remain transparent and strictly time-bound. Guddu Power Plant Rehabilitation Has Strategic Grid Importance The project’s importance extends beyond generation costs. Guddu is positioned at a critical point in Pakistan’s transmission network and the north-south power flow corridor. Restoring its full generation capability could provide the national grid with greater operational flexibility and resilience. The additional 297 MW could also become particularly valuable during periods of high demand, provided the transmission system can efficiently absorb and distribute the additional electricity. Existing Assets May Offer Pakistan a Cheaper Power Solution The Guddu Power Plant rehabilitation highlights a broader issue facing Pakistan’s energy sector. The country does not necessarily need to rely only on new generation projects to address electricity shortages and high costs. There may be significant value locked inside existing plants that are operating below capacity because of technical failures, outdated equipment or delayed maintenance. Rehabilitating such assets can potentially be faster and less capital-intensive than building new generation facilities from scratch. But the government must avoid treating rehabilitation as an end in itself. The real test will be whether Guddu actually delivers the projected Rs4.19 per unit reduction, restores 297 MW of capacity and maintains reliable operations after commissioning. If those targets are achieved, the project could become a strong example of how Pakistan can extract greater value from its existing power infrastructure while putting downward pressure on the cost of electricity.
APAG IPO Book Building Oversubscribed 1.84 Times at Rs33 Draws Strong Investor Demand
Editor pick

APAG IPO Book Building Oversubscribed 1.84 Times at Rs33 Draws Strong Investor Demand

The APAG IPO has received a strong response from investors, with the company’s book-building process ending with the issue oversubscribed by 1.84 times and the strike price finalized at Rs33 per share. The level of subscription represents an important milestone for APAG as it moves toward bringing new shareholders into the company. Strong participation during the book-building phase also indicates that investors were willing to back the company’s growth story at the final strike price. For APAG, however, the real test begins after the successful IPO process. Strong demand during book building is an encouraging signal, but it does not automatically guarantee long-term shareholder returns. APAG IPO Oversubscription Signals Market Confidence The APAG IPO attracted bids significantly above the shares available under the book-building process. With subscription reaching 1.84 times, investor participation appears to have exceeded the company’s expectations. The Rs33 strike price provides an important benchmark for APAG as it enters the next stage of its capital-market journey. It also gives incoming shareholders a clear entry valuation, although the ultimate investment case will depend on the company’s earnings performance, expansion plans, cash flows and ability to deliver sustainable growth. The strong demand can therefore be viewed as a vote of confidence, but investors should distinguish between IPO enthusiasm and fundamental business performance. APAG Welcomes New Shareholders Following the successful completion of the book-building process, APAG’s sponsors and management welcomed the company’s new shareholders and thanked investors for their strong participation. The management described the development as more than a milestone, presenting it as the beginning of a new chapter in APAG’s corporate journey. The message reflects the significance of the transaction for the company. An IPO can provide businesses with access to broader sources of capital while also increasing transparency, corporate governance expectations and public scrutiny. For APAG, becoming more closely connected with the capital market means that future financial performance is likely to face greater attention from investors. Strong IPO Demand Is Only the First Test for APAG While the APAG IPO has generated a positive headline through its 1.84 times oversubscription, investors should not confuse demand at the IPO stage with proof that the company is fundamentally undervalued. The critical questions will now shift toward how APAG deploys the capital, whether management can execute its growth strategy and whether future earnings justify investor expectations. This is where the company will need to deliver more than optimistic statements. New shareholders will ultimately judge APAG on revenue growth, profitability, cash generation and shareholder value creation. The successful book building gives APAG a strong starting point. But the more difficult task is converting investor confidence into measurable business results. What the APAG IPO Means for Investors The successful book-building process places APAG firmly under the spotlight. An oversubscription of 1.84 times demonstrates meaningful market interest, while the Rs33 strike price establishes the outcome of the initial price discovery process. The next phase will determine whether this enthusiasm can translate into sustained market confidence. For APAG, the IPO is therefore not the finish line. It is the beginning of a period in which management will have to prove that the confidence shown by investors was justified.

Pakistan Petroleum Sector Faces Investor Confidence Test as Govt Pushes Energy Security and Reform
Editor pick

Pakistan Petroleum Sector Faces Investor Confidence Test as Govt Pushes Energy Security and Reform

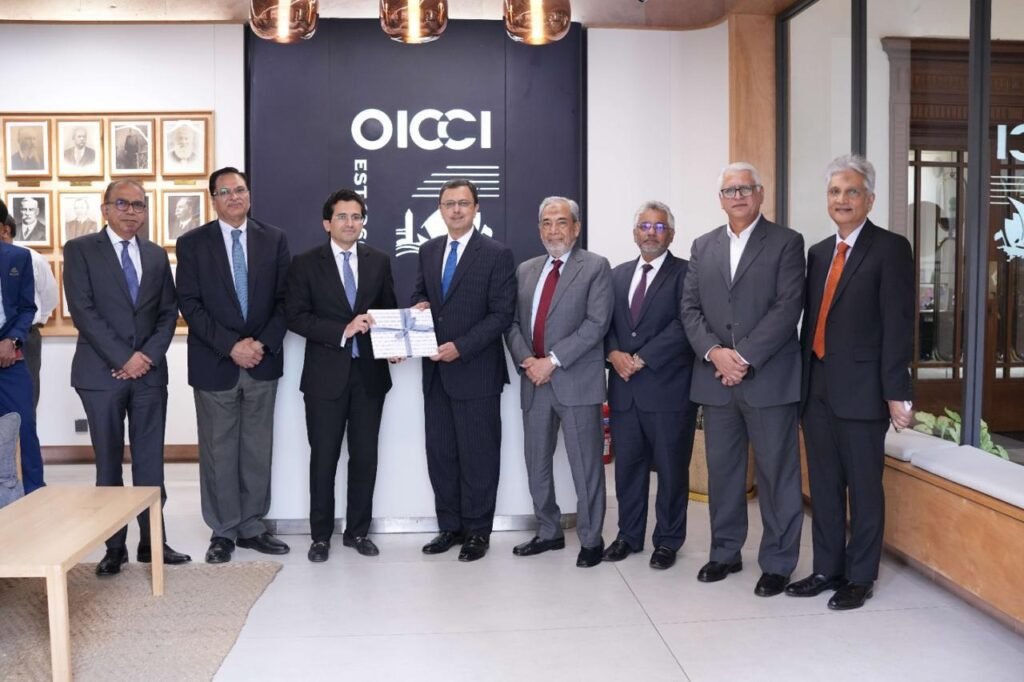
Pakistan’s petroleum sector is entering another critical phase as the government seeks fresh investment, stronger energy security and major reforms across exploration, refining and downstream markets. Federal Minister for Petroleum Ali Pervaiz Malik held separate meetings with the Overseas Investors Chamber of Commerce and Industry and Pakistan State Oil in Karachi on August 29, 2026, to discuss investment opportunities, energy security and the future direction of the sector. The meetings come at a time when Pakistan’s petroleum industry faces a difficult combination of challenges, including heavy dependence on imported energy, refining infrastructure constraints, regulatory uncertainty and concerns over the consistency of government policies. Pakistan Petroleum Sector Targets New Investment and Energy Security During his visit to OICCI, Ali Pervaiz Malik met senior chamber officials, foreign investors, industry representatives and media stakeholders. The minister outlined government initiatives aimed at strengthening exploration, modernising refining infrastructure and implementing reforms throughout the petroleum value chain. The government also highlighted bonded storage and strategic petroleum reserves as important components of its energy security strategy. Ali Pervaiz Malik said the government’s objective is to develop a more competitive and investment-oriented petroleum sector capable of meeting Pakistan’s long-term energy requirements. He said reforms are being pursued across exploration, refining and downstream markets while the government continues consultations with industry stakeholders. The message is significant because Pakistan’s energy security cannot depend solely on purchasing petroleum products from international markets. Any disruption in global oil prices, shipping routes or foreign exchange availability can quickly increase pressure on the country’s import bill and domestic consumers. Pakistan Petroleum Sector Still Faces Investor Confidence Problems The government’s engagement with foreign investors is encouraging, but dialogue alone will not solve the structural problems confronting the Pakistan petroleum sector. OICCI members reportedly stressed the importance of policy consistency, a stable tax framework, transparency and adequate security. These concerns point toward one of the industry’s biggest weaknesses: investors require certainty before committing capital to projects that can take years to recover their investment. Frequent changes in taxation, regulations, duties and commercial policies can significantly alter the economics of energy projects. For international investors, uncertainty itself becomes a cost. OICCI President Yousaf Hussain welcomed the minister’s engagement with the business community and said continued dialogue could help resolve practical industry issues while supporting investment and energy security objectives. OICCI Chief Executive and Secretary General M Abdul Aleem also stressed that predictability in the regulatory and commercial environment remains essential for foreign investors making long-term decisions. Strategic Petroleum Reserves Could Strengthen Pakistan’s Energy Defences The proposed expansion of strategic petroleum reserves deserves particular attention. Pakistan remains vulnerable to international oil price volatility and external supply disruptions. A stronger reserve system could provide the country with a buffer during global supply shocks. However, building storage capacity is only one part of the solution. The government must also establish transparent rules covering reserve ownership, financing, replenishment and emergency release. Without clear governance, strategic reserves could become another costly infrastructure initiative rather than an effective national energy security mechanism. Refinery Modernisation Could Become a Major Investment Opportunity Modernising Pakistan’s refining infrastructure could create opportunities for both domestic and foreign investors. New investment could improve refining efficiency, reduce dependence on imported refined products and potentially support a more competitive downstream market. However, investors will need more than government assurances. They will look for commercially viable returns, stable taxation, transparent regulation, reliable feedstock arrangements and clear long-term energy policies. The government’s latest engagement with OICCI therefore represents an important first step, but its real test will be implementation. Pakistan Petroleum Sector Needs Policy Continuity, Not Just New Announcements The latest discussions highlight a fundamental issue facing the Pakistan petroleum sector. The country has repeatedly announced energy reforms and investment initiatives, but sustained implementation remains the bigger challenge. If Pakistan wants to attract substantial foreign capital, the government must convert consultations into measurable reforms. Investors need predictable taxation, transparent regulation, improved security, faster approvals and commercially credible energy policies. The petroleum sector is too important to Pakistan’s economy to be managed through short-term measures alone. Energy security, refinery investment and exploration require long-term planning and institutional consistency. The government’s engagement with OICCI and PSO could therefore prove meaningful if it leads to concrete policy changes. Otherwise, the meetings risk becoming another round of consultations without producing the investment transformation Pakistan urgently needs.

Ogra Slashes RLNG Prices By Up To 27.71pc For August
Editor pick

Ogra Slashes RLNG Prices By Up To 27.71pc For August

The RLNG prices August 2026 have been significantly reduced after the Oil and Gas Regulatory Authority (Ogra) announced a month-on-month cut in Re-gasified Liquefied Natural Gas (RLNG) rates, effective from August 1. According to Ogra’s notification, the revised prices were calculated on the basis of a single LNG cargo imported by Pakistan State Oil (PSO). The latest reduction comes as Pakistan continues to face serious challenges in maintaining a stable gas supply, with gas load-shedding affecting consumers in different parts of the country. The reduction has brought RLNG prices down by more than $6 per million British thermal units (MMBtu) across the transmission and distribution networks of the country’s two major gas utilities. For the Sui Northern Gas Pipelines Limited (SNGPL) network, Ogra set the RLNG transmission price at $17.4880 per MMBtu, while the distribution price was fixed at $19.0276 per MMBtu. For the Sui Southern Gas Company Limited (SSGCL) network, the revised transmission price stands at $16.0724 per MMBtu, while the distribution price has been set at $18.1345 per MMBtu. SNGPL RLNG Transmission Price Falls 26.22pc The revised RLNG rates represent a substantial decline compared with July 2026. The SNGPL transmission price has decreased by $6.2140 per MMBtu, representing a monthly reduction of 26.22 percent. The transmission rate had been significantly higher in July, but the latest adjustment has brought the price down to $17.4880 per MMBtu. The SNGPL distribution price has also recorded a major reduction. Ogra cut the rate by $6.8112 per MMBtu, or 26.36 percent, bringing the August distribution price to $19.0276 per MMBtu. The decrease reflects lower LNG costs associated with the cargo used to calculate the latest RLNG prices. RLNG plays an important role in Pakistan’s energy supply system, particularly for meeting gas requirements when domestic production is insufficient. SSGCL Rates Decline By Nearly 28pc SSGCL also received a significant reduction in its RLNG rates. The transmission price for the SSGCL network declined by $6.1527 per MMBtu, equivalent to a reduction of 27.68 percent compared with July. Following the adjustment, the transmission rate has been set at $16.0724 per MMBtu. The distribution rate recorded an even larger reduction. Ogra lowered the SSGCL distribution price by $6.9527 per MMBtu, or 27.71 percent, bringing the revised rate to $18.1345 per MMBtu. The cut in both transmission and distribution prices marks a significant month-on-month decline for consumers and industries linked to RLNG-based gas supplies. RLNG Prices Fall Amid Gas Supply Challenges The latest reduction comes at a time when Pakistan’s gas sector continues to face supply constraints. Despite the decline in imported LNG-related prices, consumers have continued to experience disruptions in gas availability. The country relies on imported LNG to supplement declining domestic gas production and meet demand from households, power plants, industries and other sectors. RLNG prices are influenced by international LNG market conditions, cargo procurement costs, exchange-rate movements and other components incorporated into the pricing mechanism. The latest Ogra notification is based on a single LNG cargo imported by PSO. The cargo-based calculation has resulted in a considerable reduction in the rates applicable to the SNGPL and SSGCL networks. Revised RLNG Rates Take Effect From August 1 The revised rates became effective August 1, 2026, covering both transmission and distribution charges for the two major gas distribution companies. Gas Company August Transmission Price August Distribution PriceSNGPL $17.4880/MMBtu $19.0276/MMBtuSSGCL $16.0724/MMBtu $18.1345/MMBtu The largest reduction in absolute terms was recorded in the SSGCL distribution rate, which fell by $6.9527 per MMBtu. The SNGPL distribution rate posted the second-largest reduction, declining by $6.8112 per MMBtu. The new rates could provide some relief to sectors using RLNG, although the impact on end-user gas bills will depend on the applicable pricing structure, consumer category and other charges. The government and regulators continue to face the challenge of balancing affordable energy prices with the high cost of imported gas and the financial pressures facing the energy sector.

Pakistan Foreign Economic Assistance Hits $763 Million in July
Editor pick

Pakistan Foreign Economic Assistance Hits $763 Million in July

Pakistan received $763.03 million in foreign economic assistance during July 2026, marking the opening month of fiscal year 2026-27, according to the latest monthly disbursement report released by the Economic Affairs Division. The latest Pakistan foreign economic assistance figures highlight a familiar challenge for the country: a substantial share of external inflows continues to come through borrowing and budgetary support rather than directly financing productive economic activity. The July inflows came from multilateral institutions, bilateral development partners, China, and the Naya Pakistan Certificate scheme. However, the composition of the assistance raises important questions about Pakistan’s growing dependence on external financing to manage fiscal and balance of payments pressures. Pakistan Foreign Economic Assistance Reaches $763 Million Pakistan received $763.03 million in foreign economic assistance in July. Multilateral and bilateral development partners together provided $272.43 million, while other major inflows came through Chinese project financing and the Naya Pakistan Certificate scheme. The largest single component was the Naya Pakistan Certificate facility, which generated $343.99 million in foreign commercial borrowing. This included $246.67 million through the Islamic facility and $97.32 million through the conventional facility. The scale of NPC-related borrowing is significant because it shows that Pakistan’s external financing strategy is not limited to traditional development assistance. The government is increasingly relying on instruments that attract funds from overseas investors and savers to meet financing requirements. Multilateral Lenders Remain Critical to Pakistan’s Financing Multilateral institutions provided $252.83 million during July, making them a major source of Pakistan foreign economic assistance. The International Development Association was the largest multilateral contributor, providing $130.65 million. The Asian Development Bank followed with $59.17 million, while the International Bank for Reconstruction and Development contributed $29.22 million. Other multilateral inflows included $22.71 million from the Islamic Development Bank’s short-term facility, $6.57 million from the Asian Infrastructure Investment Bank, $2 million from the International Fund for Agricultural Development, $1.75 million from the Islamic Development Bank and $0.76 million from the OPEC Fund. These figures demonstrate how heavily Pakistan continues to depend on international development institutions for external financing. China Provides $146.62 Million for Chashma Nuclear Project China separately disbursed $146.62 million through a sovereign-guaranteed loan for the Chashma Nuclear Power Plant-5 project. While such financing supports long-term energy infrastructure, the sovereign guarantee means the government ultimately carries the financial obligation. This distinction matters because foreign assistance is often perceived as development funding, whereas a significant portion of these inflows represents debt that must eventually be serviced. For Pakistan, the challenge is therefore not simply attracting foreign money but ensuring that borrowed funds generate sufficient economic returns to support future debt repayments. Pakistan Foreign Economic Assistance Shows Rising Reliance on Budget Support Purpose-wise data provides an even more important picture. Non-project assistance stood at $432.73 million in July, including $343.99 million in budgetary support and $22.71 million through the IsDB short-term facility. Project-based disbursements amounted to $330.30 million. This composition deserves scrutiny. Budgetary support can provide immediate relief to government finances, but it does not necessarily expand productive capacity. If external financing repeatedly covers fiscal gaps instead of funding projects that increase exports, productivity, energy efficiency or industrial output, Pakistan risks remaining trapped in a cycle of borrowing and repayment. The July figures therefore offer more than a snapshot of foreign inflows. They expose a structural weakness in Pakistan’s economic model: external financing remains an important pillar of fiscal management. Bilateral Assistance Remains Relatively Small Bilateral development partners provided only $19.60 million during July. Germany was the largest bilateral contributor with $9.94 million, followed by Saudi Arabia with $7.42 million. France contributed $1.30 million, while Japan provided $0.94 million. The relatively modest bilateral development contribution compared with NPC borrowing, multilateral financing and Chinese project lending suggests that Pakistan’s external financing architecture is increasingly dominated by loans and market-based instruments rather than traditional bilateral development assistance. The Bigger Question Behind Pakistan Foreign Economic Assistance The headline figure of $763.03 million may appear encouraging because it represents a sizeable inflow at the beginning of the new fiscal year. However, the composition of that money is more important than the headline amount. A large portion came from borrowing, budget support and sovereign-backed financing. These inflows can strengthen short-term liquidity, but they also create future repayment obligations. Pakistan therefore needs to move beyond celebrating the size of foreign assistance and focus on the quality of financing. External funds should increasingly support export-oriented industries, energy infrastructure, technology, agriculture, water management and projects capable of generating foreign exchange. Without that shift, Pakistan foreign economic assistance could continue to provide temporary financial breathing space without resolving the deeper weaknesses that repeatedly push the country toward external financing. The July 2026 data sends a clear message: Pakistan is attracting foreign money, but the bigger economic test is whether that money can help the country become less dependent on it.

Unilever Foods Sales Surge 29%, But Shareholders Receive a Smaller Dividend
Editor pick

Unilever Foods Sales Surge 29%, But Shareholders Receive a Smaller Dividend

Unilever Pakistan Foods Limited (PSX: UPFL) delivered strong growth in the first half of 2026, with sales rising nearly 29% and profit increasing by around 40%. However, shareholders received a smaller cash payout, making the dividend decision a key part of the latest results. For the six months ended June 30, 2026, profit after tax rose to Rs4.34 billion, compared with the previous year, while the board recommended a second interim dividend of Rs350 per share, down from Rs444 a year earlier. Sales and Margins Improve UPFL’s half-year sales increased 28.9% to Rs25.26 billion, compared with Rs19.59 billion last year. Second-quarter sales also grew 32.3% to Rs12.06 billion. The company attributed the growth to stronger volumes across Knorr Noodles, Rafhan and Unilever Food Solutions. Gross profit increased to Rs10.83 billion from Rs7.53 billion, while the gross margin improved to around 42.9%, up 442 basis points. Rising Expenses Limit Profitability Despite stronger sales and margins, operating expenses increased sharply. Distribution, administrative and other expenses rose nearly 50% to Rs4.35 billion from Rs2.91 billion. Other income also declined 41% to Rs365 million. Operating profit nevertheless increased 30% to Rs6.84 billion, showing that the core business continued to perform well despite higher costs. Profit Rises While Dividend Falls Half-year EPS increased to Rs680.90 from Rs484.86, while second-quarter EPS rose to Rs349.89 from Rs222.25. However, dividend growth moved in the opposite direction. The company had already reduced its first interim dividend to Rs331 per share from Rs525 a year earlier. With the latest Rs350 payout, total H1 cash dividends reached Rs681 per share, compared with Rs969 in the previous year. The entitlement date for the second interim dividend is September 7, with share transfer books scheduled to close from September 8 to 10. Cash Flow Shows Improvement UPFL’s cash position improved considerably during the period. Net cash generated from operations reached Rs5.45 billion, compared with an outflow of Rs633 million in the same period last year. The company spent Rs601 million on plant and equipment, while cash and cash equivalents increased to Rs3.57 billion from Rs812 million at the start of the year. The stronger cash generation provides some support for the company’s financial position, even as management takes a more cautious approach to shareholder distributions. Outlook Remains Cautious The company continues to operate in an environment shaped by high living costs, inflation, commodity prices and geopolitical uncertainty. Rising administrative and distribution expenses show that stronger sales do not necessarily translate into proportional increases in shareholder returns. There is also uncertainty surrounding Unilever Plc’s planned combination of its global foods business with McCormick, which remains relevant for local investors. UPFL’s first-half results therefore present a mixed picture: strong brands, higher sales, wider margins and improved cash generation, but rising costs and a reduced dividend. The key question for investors will be whether the company can sustain its growth while protecting margins and maintaining attractive shareholder returns.

Pakistan Targets $6 Billion Refinery Investment Under Brownfield Upgrade Policy
Business, Editor pick

Pakistan Targets $6 Billion Refinery Investment Under Brownfield Upgrade Policy

Pakistan is moving closer to attracting around $6 billion in investment in its oil refining sector as the country’s five major refineries prepare to sign brownfield upgradation agreements early next month. The agreements are expected to mark the beginning of a major modernisation programme aimed at improving domestic fuel production, reducing imports and strengthening Pakistan’s energy security. Refineries Ready to Sign Upgrade Agreements Petroleum Minister Ali Pervaiz Malik recently met the management of PARCO, Pakistan Refinery Limited (PRL), National Refinery Limited (NRL), Cnergyico and Attock Refinery Limited (ARL) in Karachi. The refinery managements reportedly confirmed that preparations are complete and that they are ready to sign agreements under the Brownfield Refinery Upgradation Policy. The Petroleum Division said the agreements would provide the first major step toward implementing the policy and upgrading existing refining facilities. Focus on Euro-V Fuel Production A key objective of the programme is to enable local refineries to produce Euro-V compliant petrol and diesel. Increasing domestic production of higher-quality fuels could help Pakistan reduce its dependence on imported petroleum products. It may also strengthen supply chains and reduce exposure to international fuel price and supply disruptions. The government has also emphasised maintaining uninterrupted fuel supplies, particularly after the challenges created by disruptions around the Strait of Hormuz. Modernising Pakistan’s Refining Sector The brownfield policy follows amendments to the 2023 refining policy approved by the Cabinet Committee on Energy in July. The government considers the modernisation of existing refineries an important national priority. Planned upgrades are expected to increase petrol and diesel production, reduce furnace oil output and bring refinery operations closer to international environmental standards. For the industry, modernisation is increasingly important as global fuel specifications become more demanding and Pakistan seeks to improve the efficiency of its domestic energy infrastructure. Oil City Proposal Adds to Energy Strategy Alongside refinery upgrades, officials have also discussed developing an Oil City in Hub as a potential strategic storage and energy terminal. The proposed facility could strengthen Pakistan’s petroleum storage capacity and improve the country’s ability to manage fuel supplies during periods of international market disruption. Together, refinery modernisation and improved storage infrastructure could form a broader strategy to make Pakistan’s petroleum supply chain more resilient. $6 Billion Investment Could Reshape the Sector The proposed agreements represent a significant investment opportunity for Pakistan’s refining industry. If implemented effectively, the programme could increase local fuel production, reduce the import bill and improve energy security. However, the scale of the investment will ultimately depend on timely implementation, financing arrangements and the ability of refineries to complete upgrades within agreed timelines. The government has pledged continued cooperation with refinery operators to prevent delays and move the programme forward. For Pakistan, the brownfield initiative offers an opportunity to modernise an ageing refining base while reducing dependence on imported fuels. The real test will be whether the planned investment translates into higher production, cleaner fuels and measurable savings for the economy.

SSGC UFG Reform Takes Center Stage as Government Demands Structural Change
Editor pick

SSGC UFG Reform Takes Center Stage as Government Demands Structural Change

The government has ordered the Board of Sui Southern Gas Company Limited to prepare a comprehensive reform strategy focused on controlling unaccounted-for-gas, commonly known as UFG, as Islamabad pushes to turn the financially troubled gas utility into a more sustainable organization. Federal Minister for Petroleum Ali Pervaiz Malik issued the directive during a meeting with the SSGC Board, Managing Director and senior management in Karachi on August 27. The meeting reviewed the company’s performance, operational challenges and future reform priorities. The government’s emphasis on SSGC UFG reform highlights one of the biggest structural problems facing Pakistan’s gas distribution system. While management reported that UFG has fallen by approximately 57 percent in volumetric terms, the government’s latest demand indicates that significant efficiency and financial challenges remain. 57 Percent UFG Reduction Is Significant, But Is It Enough? SSGC management told the meeting that UFG had been reduced by around 57 percent in volume. The improvement is substantial and could strengthen the company’s finances if the reduction is sustained. However, the headline figure should not become an excuse to declare victory. UFG represents gas that enters the distribution system but is not properly accounted for through legitimate consumption. It can arise from technical losses, inefficient infrastructure, inaccurate measurement and gas theft. Every unit lost ultimately puts additional pressure on the gas sector’s finances and can contribute to higher costs for consumers or the government. This is why the government’s SSGC UFG reform agenda needs to move beyond percentage-based improvements. The real test will be whether SSGC can permanently reduce losses, recover unpaid revenues, modernize infrastructure and make those gains visible in its financial statements. Government Pushes SSGC Toward a Self Sustaining Business Model The Petroleum Minister directed the Board to develop a strategy covering operational efficiency, human resource capabilities, loss reduction, gas theft control, revenue recovery and better resource utilization. The objective is ambitious: SSGC must become financially self-sustaining while continuing to provide essential public services. The government also said gas supply has improved. There is currently no gas load shedding for K-Electric, industrial consumers and fertilizer plants, while domestic consumers are receiving gas three times a day. Gas prices have also remained unchanged over the past year, while the growth of gas circular debt has reportedly been nearly arrested. Yet these developments expose a difficult policy question. Can the government keep gas prices politically manageable while simultaneously making state owned gas companies financially viable? Without deeper structural reforms, controlling circular debt and losses could prove temporary. Single Gas Price Proposal Could Reshape Pakistan’s Energy Market Another major proposal discussed at the meeting was replacing the existing gas subsidy system based on pricing slabs with a single fair gas price. The government argues that a unified pricing structure could encourage economic activity and reduce consumer migration toward alternative fuels, while vulnerable consumers would receive targeted support through social protection programmes. This approach deserves scrutiny. A single gas price may simplify the market and reduce distortions, but it could also increase household energy costs if targeted protection is poorly implemented. The success of such a reform will depend on whether subsidies actually reach low income consumers rather than simply shifting the financial burden from one part of the gas sector to another. Balochistan Gas Supply Remains a Critical Test The government has also instructed SSGC to prioritize gas supply issues in Balochistan while addressing infrastructure constraints, technical problems and gas theft. The province presents a particularly difficult challenge because energy availability is closely connected with broader economic and political grievances. The Board welcomed the formation of a Political Committee under the Deputy Prime Minister to examine Balochistan’s longstanding challenges. However, political committees alone cannot resolve infrastructure and service delivery problems. SSGC will need sustained investment, stronger enforcement and transparent performance targets if gas availability in the province is to improve meaningfully. World Bank Reform Programme Adds Pressure on SSGC The government says it is working with the World Bank on broader gas sector reforms aimed at addressing structural weaknesses and improving financial sustainability. The involvement of an international development institution could provide technical support and reform discipline. But Pakistan’s history with state owned enterprises suggests that reform plans frequently fail when political intervention, weak accountability and poor implementation undermine them. The latest SSGC UFG reform strategy therefore needs measurable targets rather than another policy document. The Board should be judged on whether UFG falls further, revenue recovery improves, theft declines, infrastructure becomes more efficient and the company reduces its dependence on government support. For consumers, the real question is even simpler: will these reforms deliver more reliable gas without creating another financial burden?

Sazgar Engineering Profit Jumps 44% To Rs23.6 Billion Despite Margin Pressure
Editor pick

Sazgar Engineering Profit Jumps 44% To Rs23.6 Billion Despite Margin Pressure

Sazgar Engineering Works Limited (PSX: SAZEW) reported a 44% increase in net profit to Rs23.60 billion for the year ended June 30, 2026. The strong earnings growth was supported by a major increase in sales, but the results also showed growing pressure on margins, rising inventory and weaker operating cash flow. The company reported earnings per share of Rs390.51, compared with Rs270.26 a year earlier. Sales Surge As Costs Rise Faster Net sales jumped 76% to Rs191.72 billion from Rs108.69 billion. However, the cost of sales increased even faster, rising 89% to Rs145.24 billion. As a result, gross profit grew 47% to Rs46.48 billion. Gross margin declined to approximately 24.2% from 29.1%, showing that higher sales volumes did not translate into the same level of margin expansion. Four-wheelers remained a key growth driver, helping push the company’s top line sharply higher. Profit Growth Outpaces Cash Generation Operating profit increased to Rs36.45 billion, compared with Rs25.61 billion last year. However, distribution and marketing expenses rose 78% to Rs6.19 billion, while administrative costs also increased significantly. Finance costs nearly doubled to Rs454 million. Other income provided some support, increasing to Rs2.65 billion, while taxation amounted to Rs15.04 billion. Despite the higher reported profit, cash generated from operations declined to Rs9.60 billion from Rs14.11 billion. Inventory Becomes A Major Concern One of the biggest changes in the financial statements was the sharp rise in inventory. Stock-in-trade increased to Rs42.07 billion from Rs14.23 billion, nearly tripling during the year. The rise suggests that a significant portion of the company’s earnings is tied up in inventory rather than being converted into cash. Cash and bank balances consequently declined to Rs13.98 billion from Rs16.60 billion. Heavy Investment Drives Balance-Sheet Growth Sazgar also significantly expanded its production capacity. Property, plant and equipment increased to Rs23.02 billion from Rs7.94 billion, while capital expenditure reached Rs15.64 billion. Diminishing musharakah financing rose sharply to Rs5.19 billion from just Rs50 million, while trade and other payables increased to Rs30.72 billion. Total assets more than doubled to Rs81.65 billion, while equity reached Rs43.02 billion. The expansion is therefore being supported by retained earnings, supplier financing and additional Islamic financing alongside the company’s investment programme. Final Dividend Takes Total FY26 Payout To Rs70 Sazgar declared a final cash dividend of Rs20 per share, taking the total FY26 payout to Rs70 per share after interim dividends. The total payout is higher than the Rs52 per share distributed last year, but represents only around 18% of FY26 earnings. The relatively low payout suggests that management is retaining a significant portion of earnings to support capacity expansion and working-capital requirements. Strong Growth Comes With New Risks Sazgar’s FY26 results present a mixed picture. The 76% increase in sales and 44% rise in profit demonstrate strong business growth, while the dividend has also increased. However, the decline in gross margin, sharp inventory build-up, lower operating cash flow and increased financing indicate that expansion is becoming more capital-intensive. For investors, the key issue going forward will be whether Sazgar can convert its growing sales and production capacity into stronger margins and sustainable cash generation.

NBP Profit Falls 25% As Deposits Shrink, No Dividend Declared
Editor pick

NBP Profit Falls 25% As Deposits Shrink, No Dividend Declared

National Bank of Pakistan (PSX: NBP) reported a 25% decline in unconsolidated profit after tax to Rs32.41 billion for the half year ended June 30, 2026, compared with Rs43.47 billion a year earlier. Second-quarter profit dropped to Rs15.68 billion from Rs22.02 billion, while half-year earnings per share fell to Rs15.23 from Rs20.43. The bank’s board also recommended no cash dividend, bonus shares or rights issue for the period. Lower Interest Income Weighs On Profit NBP’s core interest earnings came under pressure as interest rates moved lower. Mark-up earned declined to Rs361.71 billion from Rs410.90 billion, while mark-up expense fell to Rs261.65 billion from Rs280.34 billion. As a result, net interest income dropped 23% to Rs100.06 billion, compared with Rs130.56 billion in the same period last year. Non-interest income provided limited support, rising slightly to Rs27.57 billion. However, fee and commission income fell to Rs13.64 billion from Rs14.75 billion. Rising Expenses Add Pressure The bank’s operating expenses increased to Rs65.52 billion from Rs59.11 billion. Profit before provisions fell sharply to Rs62.09 billion from Rs98 billion, showing that weaker core income and higher expenses continued to affect profitability. NBP did benefit from credit provisions, which moved to a net reversal of Rs8.26 billion, compared with a net charge of Rs4.77 billion a year earlier. Without this reversal, the decline in underlying earnings would have been even more pronounced. Deposits Decline As Borrowings Rise NBP’s deposits and other accounts fell to Rs4.22 trillion, down from Rs4.43 trillion at the end of December 2025. Advances also declined slightly to Rs1.31 trillion from Rs1.34 trillion. At the same time, borrowings surged to Rs2.82 trillion from Rs1.69 trillion, while investments increased to Rs5.67 trillion from Rs4.92 trillion. The figures indicate that the bank relied more heavily on borrowed funds while its deposit base contracted. Stock Faces Pressure After Results NBP shares also came under pressure following the results, with the stock falling from around Rs202 to approximately Rs188.80, a decline of more than 6% during the session. The market reaction reflects concerns over weaker profitability, shrinking deposits and the absence of an interim dividend. Dividend Decision Draws Attention NBP had paid a Rs35 per-share dividend for 2025, but shareholders will receive no interim cash payout for the current half year under the board’s recommendation. The decision is particularly notable as investors continue to assess banking stocks based on both earnings and dividend returns. With profits down 25%, deposits declining and borrowings rising sharply, NBP’s latest results point to a more challenging operating environment for the state-owned bank.

Scroll to Top